

Blogs
PW Consulting: BIM Market Hits $113M in 2025, Projected 13.05% CAGR to $267.4M by 2032
By PW Consulting, 2026-09-16
The Digital Backbone of Construction: Unlocking Strategic Value in the 2026 BIM Market
The construction industry stands at a critical inflection point, where digital transformation is no longer optional but existential. Building Information Modeling (BIM) has evolved from a niche technological advantage into the central nervous system of modern infrastructure development. As we navigate through 2026, understanding the trajectory of this market is vital for stakeholders ranging from civil engineering firms to software investors. Our latest comprehensive market research provides a granular look at this ecosystem, offering the intelligence required to navigate the next cycle of growth.
Recent historical data underscores the resilience and accelerating momentum of the sector. The market has demonstrated consistent expansion over the past half-decade, moving from a valuation of 60.0 million USD in 2020 to approximately 113.0 million USD in 2025. This historical trajectory sets the stage for a forecast period defined by robust acceleration. Projections indicate that the market will reach 128.71 million USD by the end of 2026, eventually climbing toward 267.4 million USD by 2032. This growth pattern corresponds to a compound annual growth rate of 13.05 percent during the forecast horizon, signaling a high-confidence environment for capital allocation and strategic planning.
However, top-line numbers only tell a fraction of the story. The true value for enterprise decision-makers lies in understanding the underlying mechanics driving this expansion. Our report dissects the ecosystem to reveal where value is being created, which geographies are leading the charge, and how the competitive landscape is consolidating. This article serves as a strategic preview of those findings, highlighting the critical dynamics that will define success in 2026 and beyond.
Market Trajectory and Growth Drivers
The forecast period from 2026 to 2032 is expected to be characterized by a shift from adoption to optimization. While the initial push for BIM was driven by regulatory compliance and basic digitalization, the current phase is fueled by efficiency mandates and integrate data workflows. The steady increase from 146.71 million USD in 2027 to 208.68 million USD in 2030 suggests that demand is becoming less sensitive to economic fluctuations, embedding itself deeper into operational budgets.
Our analysis identifies several key catalysts propelling this growth. The industry is moving beyond static 3D modeling toward dynamic information management. This shift is not merely technological but procedural, requiring firms to rethink how data is handled from preconstruction through postconstruction phases. The research highlights that while certain phases traditionally dominate revenue share, the growth rate is accelerating in areas related to lifecycle management and digital twin integration. Understanding these shifts is crucial for vendors positioning their solutions and for firms selecting partners to ensure long-term compatibility.
Furthermore, the revenue unit analysis indicates a significant reliance on specific type segments. The market remains heavily weighted toward software solutions compared to services, reflecting a preference for scalable digital tools over manual consultancy. Yet, the services segment continues to play a pivotal role in implementation and customization, ensuring that organizations can actually derive value from the software licenses they purchase. This balance between software and services is a key consideration for investors assessing recurring revenue models versus one-off service engagements.
Regional Dominance and Emerging Hubs
Geographic distribution remains a critical component of market strategy. Current analyses point to a mature landscape in developed economies, yet the potential for expansion in emerging regions is substantial. North America continues to command a significant share of the global revenue, reflecting early adoption rates and a high density of large-scale infrastructure projects. Europe follows as a strong second, driven by stringent regulatory frameworks and public sector mandates for digital delivery.
Asia Pacific represents a dynamic growth engine, with rapid urbanization and increasing investment in smart infrastructure fueling demand. While the share values vary, the momentum in this region often outpaces mature markets in terms of percentage growth. Latin America and the Middle East and Africa, while currently representing smaller portions of the total revenue, are identified as areas where strategic entry could yield high long-term returns. Our report provides a detailed breakdown of these regional nuances, helping entities identify where to focus sales efforts or where to seek partnership opportunities.
It is essential for decision-makers to recognize that regional preferences are not static. Local regulations, labor costs, and technological infrastructure influence how BIM is deployed. For instance, markets with higher labor costs may prioritize automation and clash detection tools to reduce rework, whereas developing regions might focus on basic coordination and documentation capabilities. The research delves into these behavioral differences to provide a localized view of global trends.
Building Management System Market
Competitive Landscape and Key Players
The BIM market is defined by a mix of established giants and specialized innovators. Market concentration metrics indicate a moderately fragmented environment, with the top three players capturing a combined share of approximately 25.5 percent and the top five holding around 30.2 percent. This suggests that while there are dominant forces, there is still ample room for niche players or specialized solutions to thrive, particularly in vertical-specific applications.
Autodesk remains a cornerstone of the ecosystem, headquartered in San Francisco. Their portfolio, including Autodesk Revit for parametric 3D modeling and Autodesk Forma, continues to set industry standards. Recent updates in 2026 have focused on enhancing modeling workflows and cloud-based cost management. The company has also expanded its API ecosystem to drive third-party integration, reinforcing its platform strategy and recurring revenue potential. Their continuous updates, such as the Revit 2026 launch with accelerated graphics and the BIM 360 Cost Management update, demonstrate a commitment to maintaining technological leadership.
Bentley Systems , based in Exton, Pennsylvania, maintains a strong focus on infrastructure and digital delivery. Their offerings like ProjectWise for data governance and SYNCHRO for 4D planning are integral to large-scale engineering projects. The emphasis on digital twins through iTwin positions them uniquely for lifecycle management beyond the construction phase. As the industry moves toward information-centric standards, Bentley's focus on data governance aligns well with emerging regulatory requirements.
Nemetschek Group in Munich operates as a powerful conglomerate with diverse holdings including ALLPLAN. Their recent 2026 updates for ALLPLAN emphasize multilayer finishes modeling and BIM-compliant detailing, reflecting a push toward granular construction accuracy. Additionally, the transition of subsidiary Graphisoft away from perpetual licenses toward subscription models signals a broader industry shift toward recurring revenue streams, changing how customers access and pay for architectural tools like Archicad.
Graphisoft , headquartered in Vienna, continues to innovate in the architectural space. The release of Archicad 29 in late 2025 introduced AI Assistant features and enhanced MEP Designer toolkits. However, their decision to terminate perpetual licenses by the end of 2026 forces a market-wide transition to subscription licensing. This move impacts cash flow planning for many firms and underscores the industry's pivot toward cloud-based, continuously updated software environments.
Dassault Systèmes brings a different dimension with their 3DEXPERIENCE platform. Based in France, they focus on integrating BIM with broader digital twin capabilities across the AEC industry. Their use of CATIA for integrated BIM suggests a strong orientation toward complex manufacturing and high-precision building requirements, appealing to clients who need deep engineering integration.
Regulatory Shifts and Operational Dynamics
The regulatory environment is undergoing a significant transformation that directly impacts market dynamics. The release of the ISO 19650:2026 Draft International Standard marks a pivotal shift from model-centric to information-centric lifecycle management. This revision emphasizes information management over traditional BIM terminology, introducing new requirements for data validation, exchange, and lifecycle maintenance. For organizations, this means compliance is no longer just about producing a model but about ensuring the integrity and usability of data throughout the asset's life.
Simultaneously, cloud hosting and data privacy rules are reshaping workflows. New rules effective February 2026 regarding Revit Cloud Model downloads require updates to workflows for unpublished linked files. Compliance in cloud-based BIM environments is now more complex, necessitating careful attention to data governance. Additionally, Autodesk's platform consolidation using Forge APIs aims to drive third-party integration, which benefits the ecosystem but also increases dependency on specific cloud architectures. These technical and regulatory shifts create barriers to entry but also solidify the moats for platforms that can ensure seamless compliance.
Report Scope and Strategic Utility
To fully capitalize on these opportunities, stakeholders need more than high-level trends. Our comprehensive report offers a deep dive into the operational specifics that drive decision-making. The study is structured to provide actionable intelligence across multiple dimensions, ensuring that readers can translate data into strategy.
- Historical and Forecast Analysis: Detailed year-over-year data from 2020 through 2032, allowing for trend extrapolation and budget forecasting.
- Segmentation Deep Dives: Comprehensive breakdowns by application, type, and region, revealing where growth is concentrated without relying on surface-level aggregates.
- Company Profiling: In-depth profiles of key market participants, including their strategic positioning, recent product launches, and technological focus.
- Regulatory Impact Assessment: Analysis of how new standards like ISO 19650:2026 and cloud compliance rules affect operational workflows and vendor selection.
- Growth Drivers and Restraints: Identification of the specific factors accelerating adoption versus those posing challenges, such as labor shortages or integration complexity.
This research is designed for chief strategy officers, market analysts, and investment managers who require precision. Whether you are evaluating market entry, assessing competitor moves, or planning long-term R&D investments, the granularity provided in the full report is essential. We have intentionally omitted specific percentage splits and exact revenue figures for segments in this overview to preserve the proprietary value of the full dataset.
Conclusion: The Path Forward
The BIM market in 2026 is defined by convergence—of data, regulations, and platforms. The growth from 113.0 million USD to a projected 267.4 million USD by 2032 is not just a number; it represents a fundamental restructuring of how the built environment is designed, constructed, and managed. Success in this environment requires a clear understanding of where the market is heading and who is leading the way.
Building Information Modeling (BIM) Market
Our full market research report provides the detailed compass needed to navigate this landscape. By securing access to the complete intelligence package, your organization can move beyond speculation and make decisions grounded in rigorous data. We invite you to explore the full findings to unlock the specific insights required to drive your strategic agenda in this evolving digital construction era.
For detailed analysis of this topic, please visit the official page: Building Information Modeling (BIM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Sodium Hypochlorite Generator Market to Hit USD 239M by 2032, 8.7% CAGR
By PW Consulting, 2026-09-16
Navigating the Sodium Hypochlorite Generator Market: Strategic Intelligence for 2026 Decision-Makers
As global industries accelerate the transition toward decentralized and sustainable water treatment solutions, the sodium hypochlorite generator market has emerged as a critical battleground for infrastructure investment, public health modernization, and operational resilience. For executives, municipal planners, and industrial operators navigating the 2026 landscape, understanding the trajectory of on-site chemical generation is no longer a technical exercise—it is a strategic imperative. PW Consulting’s latest market intelligence study dissects the forces shaping this sector, offering a rigorous, data-backed framework to align capital allocation, supply chain strategy, and regulatory compliance with the decade ahead.
The market has already demonstrated remarkable momentum over the past half-decade. Valued at approximately 90.6 million USD in 2020, it has consistently expanded through successive years, crossing the 116.5 million USD threshold by 2023 and climbing to an estimated 134.0 million USD in 2025. This historical trajectory underscores a structural shift rather than a cyclical fluctuation. Looking forward, our forecast model projects sustained expansion through the end of the decade, with revenue expected to approach 239.0 million USD by 2032. The implied compound annual growth rate of 8.7 percent reflects deepening adoption across water utilities, industrial facilities, and commercial operations that are actively seeking to mitigate supply chain vulnerabilities, reduce reliance on bulk chemical transport, and improve on-site disinfection reliability. These macro figures, while compelling, represent only the surface of a highly nuanced landscape. The true strategic advantage lies in understanding how regional deployment patterns, capacity tiering, application-specific demand, and shifting compliance requirements intersect to create asymmetric opportunities for early movers.
The 2026 Decision Matrix: Why Traditional Procurement Models Are Falling Short
For years, water disinfection procurement followed a familiar playbook: order bulk sodium hypochlorite, manage storage and handling risks, and absorb the volatility of chemical shipping and seasonal supply bottlenecks. The 2026 operating environment has rendered that model increasingly fragile. Infrastructure modernization initiatives are accelerating, and public and private operators alike are recognizing that on-site electrolysis systems offer a compelling alternative to centralized chemical logistics. The strategic calculus has shifted from simple cost-per-gallon comparisons to total lifecycle value, encompassing regulatory compliance, worker safety, environmental footprint, and resilience against transport disruptions.
Utilities and industrial facilities are now evaluating generator deployments through a multi-dimensional lens. Municipal operators must weigh NSF/ANSI/CAN 61 certification pathways for drinking water applications against evolving state-level procurement standards, while industrial managers must align system capacities with fluctuating production schedules and brine feedstock availability. Meanwhile, commercial and recreational operators are exploring compact generation units that can deliver consistent disinfection without the logistical overhead of chemical delivery. The procurement cycle has lengthened, the technical evaluation criteria have multiplied, and the competitive field has matured. Organizations that approach this transition with fragmented vendor comparisons or outdated cost models risk overcommitting to suboptimal configurations. The market demands a structured, forward-looking evaluation framework—and that is precisely what our research delivers.
Decoding the Competitive Arena
The sodium hypochlorite generator market is characterized by a concentrated yet strategically active competitive landscape. CR3 firms account for approximately 35 percent of market revenue, while the top five players collectively command around 45 percent. This concentration reflects the technological barriers to entry, the capital intensity of electrolytic system development, and the lengthy qualification cycles required to secure municipal and industrial contracts. Yet the market remains dynamic, with established players continuously refining system architectures, expanding application portfolios, and responding to emerging compliance mandates.
Among the most prominent participants, De Nora, headquartered in Milan, Italy, has built a recognized portfolio around its ClorTec® on-site low-strength sodium hypochlorite generators, alongside the CECHLO-MS high-strength systems that leverage electrolytic brine electrolysis for demanding disinfection environments. The company’s dual focus on low-strength and high-strength architectures positions it to serve both routine municipal water treatment and specialized industrial applications where concentration precision matters.
Xylem Inc., based in Chicago, Illinois, has established a strong presence through its OSEC® branded on-site hypochlorite generation systems, including the B-Plus, B-Pak, and L series. These platforms are engineered for municipal, aquatics, and industrial water disinfection, and their electrolytic process design aligns with utilities seeking to transition away from bulk chemical handling. Xylem’s integration of generation technology within broader water infrastructure offerings gives it a distinctive value proposition for operators pursuing end-to-end system optimization.
Sodium Hypochlorite Generator Market
Ecolab Inc., headquartered in St. Paul, Minnesota, brings a different dimension to the market through its eChlorine® electrolytic sodium hypochlorite generation systems. Designed for on-site production at the point of use, these systems have found particular traction in healthcare and hospitality environments where localized disinfection control, safety, and operational flexibility are paramount. Ecolab’s service-oriented model and cross-sector expertise allow it to address compliance and hygiene requirements that extend beyond traditional water treatment boundaries.
Electrolytic Technologies, operating in the United States, rounds out the competitive core with its Klorigen™ systems, which generate high-strength sodium hypochlorite in the 10 to 15 percent range alongside chlorine gas for municipal water and wastewater disinfection as well as industrial applications. This dual-output capability reflects a differentiated engineering approach that appeals to facilities seeking integrated disinfection chemistry rather than isolated hypochlorite production.
The competitive field is not static. Recent procurement activity and industry engagement signal where demand is crystallizing and where regulatory attention is intensifying. In March 2026, the City of Westminster issued a request for proposals for the purchase and delivery of two on-site sodium hypochlorite generation systems, illustrating how mid-sized municipal operators are moving from evaluation to execution. In November 2025, the City of Tampa’s Water Department completed construction of a new on-site sodium hypochlorite generation facility to produce liquid bleach on-site for disinfection, underscoring the growing momentum behind utility-scale deployments. Meanwhile, the Chlorine Institute scheduled its 2026 Annual Meeting with a focused agenda on sodium hypochlorite manufacturers and on-site chemical generator compliance, signaling that industry standardization and regulatory alignment will remain central themes throughout the forecast period.
Sodium Hypochlorite Market
Regulatory Realities and Infrastructure Tailwinds
No strategic assessment of this market can be separated from the regulatory and infrastructure context that shapes procurement decisions. On-site generation is not merely a technology substitution; it is an operational model change that intersects with drinking water certification, environmental verification, and standards development. The NSF/ANSI/CAN 61 certification framework applies to on-site generated sodium hypochlorite systems used in drinking water treatment, and compliance with these requirements has become a baseline expectation for municipal procurement teams evaluating system reliability and public health protection.
Parallel to certification requirements, the EPA Environmental Technology Verification program has confirmed the performance of on-site hypochlorite generation systems for primary and residual disinfection, reinforcing the technical credibility of electrolytic approaches in environments where consistent disinfection efficacy must be demonstrated. These verification pathways are increasingly referenced in procurement documentation and technical evaluation scores, making them a practical consideration rather than an abstract regulatory footnote.
Beyond drinking water, evolving standards and compliance expectations are shaping adjacent markets. The EN 18087:2026 standard sets requirements for in-situ chlorine dioxide generation from sodium chlorite, reflecting broader momentum toward on-site chemical generation and stricter controls over disinfection chemistry handling. While this standard addresses a different chemical pathway, it illustrates the regulatory trajectory: authorities are formalizing performance, safety, and operational expectations for decentralized generation systems, and manufacturers able to align their architectures with emerging standards will gain a distinct advantage in qualification processes.
Infrastructure dynamics further reinforce demand. Utility infrastructure upgrades are driving demand for on-site generators as operators seek to replace bulk chemical deliveries with more resilient, locally controlled production. This trend is reinforced by the practical realities of brine electrolysis systems, which use diluted salt solution as the primary electrolyte feedstock. The relative availability and logistical simplicity of salt-based feedstocks, combined with the reduction in hazardous chemical transport, make on-site generation an increasingly attractive option for facilities reevaluating their supply chains. These dynamics do not operate in isolation; they interact with regional procurement cycles, utility capital planning horizons, and industrial production requirements, creating a complex but navigable landscape for organizations that have access to granular, forward-looking intelligence.
Inside the PW Consulting Research Framework
Our study is structured to convert market complexity into actionable decision support. Rather than presenting abstract trends, the report maps the operational, financial, and competitive parameters that executives and technical leaders must evaluate before committing to on-site generation investments. The analysis covers the full forecast window from 2026 through 2032, anchored in a verified historical base that traces market development from 2020 onward. This temporal span allows readers to distinguish between short-term procurement cycles and longer structural shifts, ensuring that investment theses are calibrated to realistic adoption timelines.
The report examines capacity segmentation patterns, differentiating between lower-capacity systems designed for localized or intermittent disinfection needs and higher-capacity architectures suited to continuous utility-scale or large industrial operations. These capacity tiers are not merely technical specifications; they determine footprint requirements, brine handling logistics, maintenance cadences, and the economics of scale that vary significantly across deployment contexts. Our analysis unpacks how these capacity splits influence procurement strategy, vendor selection criteria, and total cost of ownership across different operational profiles.
Application-level demand is similarly dissected. Municipal water and wastewater disinfection remains a foundational driver, but the market also encompasses industrial process disinfection, food industry hygiene applications, and swimming pool and recreational water treatment. Each application segment carries distinct compliance expectations, 화학 concentration requirements, and operational rhythms. By mapping these application dynamics without oversimplifying them, the report equips decision-makers to identify where their organization’s operational profile aligns with the strongest demand signals and where cross-segment learning can accelerate evaluation timelines.
Regional deployment patterns are analyzed with attention to market maturity, procurement pacing, and infrastructure readiness. Rather than reducing regional variation to static share percentages, the research contextualizes how North American, European, Asia Pacific, Latin American, and Middle East and Africa markets differ in terms of utility modernization cadence, regulatory emphasis, and the pace at which bulk chemical delivery models are being supplemented or replaced by on-site production. This regional framing is critical because the same generator architecture may present very different risk-return profiles depending on the local procurement environment and infrastructure context.
Competitive positioning is evaluated through a combination of technology architecture, application coverage, geographic reach, and recent procurement momentum. The report does not stop at company descriptions; it examines how incumbent players are leveraging their system portfolios, service networks, and compliance credentials to shape procurement outcomes, and where gaps in application coverage or regional presence may create openings for new entrants or strategic partnerships. Recent project completions, RFP activity, and industry meetings are integrated into this analysis to connect high-level competitive positioning with real-world procurement behavior.
How to Translate This Intelligence Into 2026 Action
The strategic value of this research lies in its applicability to concrete decision points. For capital planners, the forecast trajectory and segmentation framework support scenario-based budgeting, helping organizations align procurement timing with capacity availability and financing cycles. For technical evaluation teams, the report’s treatment of certification pathways, brine electrolysis feedstock considerations, and performance verification provides a structured basis for vendor qualification and specification development. For commercial and corporate strategy leaders, the competitive concentration data, company profiles, and recent procurement signals offer a lens for assessing partnership opportunities, differentiation potential, and market entry timing.
Organizations that treat on-site sodium hypochlorite generation as a commodity procurement decision risk underestimating the operational and compliance nuances that determine long-term success. Those that approach it as a strategic infrastructure investment, grounded in robust market intelligence, are better positioned to select the right system architecture, align procurement with regional readiness, and anticipate the regulatory developments that will shape qualification standards in the years ahead.
The complete PW Consulting market research study delivers the detailed segmentation data, regional deployment context, application-level demand mapping, and competitive intelligence required to build a decisive 2026 strategy. We invite executives, procurement leaders, and technical decision-makers to access the full report, where the macro trajectory outlined here is expanded into the granular, actionable intelligence necessary to navigate this market with confidence.
For detailed analysis of this topic, please visit the official page: Sodium Hypochlorite Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High-Purity IPA Market to Reach $344.8M by 2032 at 6.98% CAGR
By PW Consulting, 2026-09-16
Strategic Imperative in High-Purity Isopropyl Alcohol: Navigating the 2026 Market Landscape
In the rapidly evolving landscape of advanced materials, High-purity Isopropyl Alcohol (IPA) stands as a critical enabler for two of the most transformative sectors of the 21st century: semiconductor manufacturing and pharmaceutical production. As industries push toward nanometer-scale precision and stringent regulatory compliance, the demand for solvents with ultra-high purity specifications has never been more acute. PW Consulting is pleased to introduce our latest comprehensive market intelligence report, designed to equip strategic decision-makers with the foresight required for 2026 and beyond. This analysis delves into the complex interplay of technological advancement, supply chain resilience, and shifting regional dynamics that define the high-purity IPA market.
Our research provides a granular examination of the market from 2020 through 2025, establishing a baseline of historical performance, before projecting trends across the forecast period from 2026 to 2032. For corporate strategists, investors, and procurement leaders, the ability to distinguish between transient fluctuations and structural shifts is vital. This report offers more than just top-line figures; it delivers a diagnostic of the competitive environment, regulatory currents, and raw material volatilities that will dictate margin structures and supply security over the coming years. The strategic value of this intelligence lies in its capacity to transform raw data into actionable roadmaps, enabling stakeholders to anticipate demand surges, evaluate supplier viability, and optimize cost structures in an increasingly competitive global arena.
Market Trajectory: Resilience and Acceleration
The macroeconomic environment for high-purity IPA has demonstrated remarkable resilience over the past half-decade, characterized by a steady upward trajectory in revenue. From a base of 163.15 million USD in 2020, the market has navigated various challenges, including pandemic-induced disruptions and logistics bottlenecks, to reach a valuation of 215.0 million USD by 2025. This historical progression underscores the inelastic nature of demand in core application areas, particularly where high-purity solvents are non-substitutable inputs for critical processes.
Looking ahead to the forecast period, the market is poised for accelerated expansion. Starting from 235.07 million USD in 2026, the revenue landscape is projected to climb consistently, reaching 344.8 million USD by 2032. This growth trajectory is underpinned by a Compound Annual Growth Rate (CAGR) of 6.98 percent, reflecting sustained investment in advanced electronics, clean energy technologies, and life sciences. The forecast is not merely a linear extrapolation; it accounts for the varying maturation rates of market segments and the impact of capacity expansions by key industry participants. Stakeholders analyzing these figures must look beyond the aggregate numbers to understand the divergent growth vectors within the market. The report dissects these nuances, offering scenario-based insights that help organizations prepare for both baseline expectations and high-growth contingencies.
Segmentation Drives Strategic Differentiation
While the overall market growth is impressive, the true strategic opportunity lies in the segmentation of demand. The high-purity IPA market is not monolithic; it is defined by distinct purity thresholds and application specificities that command different pricing dynamics and supply chain requirements. By purity, the market spans from standard high-purity grades to ultra-high-purity electronic grades that meet rigorous parts-per-billion impurity limits. The report evaluates the competitive positioning of grades such as the 99.9% to 99.99% high-purity range, which caters to broad industrial needs, against the premium Electronic Grade (>99.99%) segment, which is essential for semiconductor wafer fabrication and advanced packaging. Additionally, the "Other Grades" category, including pharmaceutical and specialty variants, represents a vital niche where regulatory compliance and certification become key differentiators.
The application landscape further illustrates the market's bifurcation. Semiconductor wafer cleaning remains the dominant driver of value, fueled by the relentless scaling of logic and memory chips, the rise of advanced packaging techniques, and the need for defect-free surface preparation. However, the Pharmaceutical and Cosmetics sector, as well as Electronics Assembly and Cleaning, contribute significant and growing demand streams. Each application vertical imposes unique specifications regarding water content, acidity, and organic impurities. For instance, the report details how semiconductor manufacturers are imposing increasingly stringent requirements, such as keeping C7-12 acetal impurities below 100 parts per billion per USP/EP monographs to support 2nm node cleaning processes. Similarly, pharmaceutical-grade IPA must meet strict FDA cGMP standards, including maximum 0.5% water content and acidity under 0.002%. These technical barriers create moats for suppliers capable of consistent quality assurance, influencing sourcing strategies and vendor selection criteria.
Recovered Isopropyl Alcohol Market
Regional dynamics add another layer of complexity. The market analysis examines consumption patterns across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The Asia Pacific region, home to a dense concentration of semiconductor fabs and pharmaceutical manufacturers, exhibits distinct demand characteristics and supply chain interdependencies. Europe and North America maintain strong positions driven by established industrial bases and robust regulatory frameworks. Emerging regions present both opportunities for expansion and risks related to infrastructure maturity. Our segmentation analysis provides the framework to assess regional exposure, identify arbitrage opportunities, and align supply networks with demand centers without oversimplifying the geopolitical and logistical realities on the ground.
Competitive Landscape and Capacity Evolution
The competitive environment for high-purity IPA is characterized by a mix of global chemical majors, specialized electronics material suppliers, and regional players. With a CR3 of 24.6 percent and CR5 of 26.2 percent, the market remains relatively fragmented, allowing for active competition and innovation, yet concentration is gradually increasing in high-value segments. Key players such as ExxonMobil Chemical, Eastman Chemical Company, LyondellBasell Industries, Dow Inc., Mitsubishi Chemical Corporation, LCY Chemical Corporation, Tokuyama Corporation, LG Chem Ltd., Shell Chemicals, BASF SE, INEOS Group, and GJ Chemical are actively shaping the market through capacity expansions, product innovation, and strategic partnerships.
Recent developments highlight the strategic importance of ultra-high-purity capabilities. For example, ExxonMobil Chemical announced a significant USD 100 million investment in March 2025 to upgrade its Baton Rouge plant, targeting the production of 99.999% ultra-high-purity IPA starting in 2027 to support semiconductor chip manufacturing. This move reflects a broader industry trend where integrated supply chains and plant upgrades are prioritized to secure the "EastaPure-equivalent" grades demanded by leading fabs. Similarly, Eastman Chemical Company has reinforced its position by introducing its EastaPure™ ultrahigh-purity IPA (4N grade) in its active catalog, specifically targeting semiconductor wafer fabrication wet cleaning and drying applications. These product launches underscore the race to capture market share in the premium electronic grade segment.
Capacity expansions are not limited to the United States. LyondellBasell Industries expanded its Texas facility IPA production by 25 percent in November 2025 to meet growing North American demand, underscoring the region's strategic focus on domestic supply security. In Asia, LCY Chemical Corporation launched its LCY Advanced Formulations portfolio in September 2025, including electronic-grade high-purity IPA for advanced packaging and wafer cleaning, while Tokuyama Corporation continues to supply ultra-high-purity grades essential for 2nm semiconductor cleaning processes. Other players like Mitsubishi Chemical, LG Chem, and Deepak Fertilisers are also upgrading facilities to enable full-scale production and export of high-grade pharma-certified IPA, signaling a global alignment of supply capabilities with end-market needs. The report provides a deep-dive company profile for each major participant, analyzing their product portfolios, geographic footprint, recent investments, and competitive differentiators, offering readers the intelligence needed to benchmark suppliers and anticipate shifts in market power.
Market Dynamics: Raw Materials and Regulatory Pressures
A sophisticated market analysis must address the underlying forces that influence pricing, availability, and risk. Raw material dynamics play a pivotal role in the economics of high-purity IPA, given its chemical derivation from acetone via hydrogenation. Acetone price volatility can propagate through the value chain, affecting production costs and margin stability. Our research integrates current market intelligence on acetone pricing, noting that CIF acetone prices in North America have observed significant levels, with Northeast Asia FOB prices showing distinct regional differentials. Furthermore, geopolitical events have impacted supply flows; disruptions linked to the US-Iran conflict in 2025 tightened Middle East acetone supply, which in turn elevated European CIF acetone prices. These fluctuations highlight the importance of monitoring upstream commodity markets and securing diversified sourcing strategies. The report explores how suppliers manage these cost pressures through long-term contracts, integration, and hedging, and how these strategies affect the pricing power of high-purity grades.
Regulatory compliance constitutes another formidable driver of market structure. The transition to advanced technology nodes in semiconductors has necessitated tighter control over impurities, with industry standards increasingly referencing USP/EP monographs and ISO 9001 certifications. The requirement for <100 ppb C7-12 acetal impurities in high-purity IPA for 2nm node cleaning exemplifies the technical chasm between standard grades and electronic grades. In the pharmaceutical sector, adherence to FDA cGMP regulations, including limits on water content and acidity, is not optional but a license to operate. These regulatory frameworks create high entry barriers, rewarding suppliers with robust quality management systems and advanced purification technologies. BASF SE, for instance, supplies high-purity IPA grades for pharmaceutical and electronic applications leveraging advanced purification tech, while INEOS Group produces high-purity IPA including bio-based variants to meet evolving sustainability and performance metrics in EU and global markets. The report analyzes how these regulatory and technological demands shape supplier selection, contract negotiation, and the overall cost of quality.
Unlocking the Full Intelligence: Why This Report Matters for 2026
As we move deeper into 2026, the margin for error in strategic planning is shrinking. The high-purity IPA market is influenced by a confluence of factors: rapid technological advancement in semiconductors, evolving regulatory landscapes, volatile raw material inputs, and shifting geopolitical trade patterns. Decision-makers cannot afford to rely on outdated benchmarks or generalized industry narratives. PW Consulting's High-purity Isopropyl Alcohol Market report is engineered to provide the depth, accuracy, and actionable insights required to navigate this complexity.
This report offers a comprehensive toolkit for strategic analysis. It includes detailed market sizing and forecasts that isolate growth drivers by purity and application, enabling precise demand modeling. It profiles the key companies, detailing their recent developments, capacity strategies, and product innovations, allowing you to assess competitive threats and partnership opportunities. It maps the regulatory environment, identifying compliance risks and standards that will impact your supply chain eligibility. It examines raw material dynamics, providing context on cost structures and price volatility drivers. And it analyzes regional dynamics, helping you optimize your geographic exposure and logistics strategy.
Crucially, the report does not merely present data; it interprets it. The segmentation splits, historical performance, and forecast trajectories are woven into a narrative that highlights strategic implications. You will gain an understanding of which purity grades are seeing the most aggressive capacity investment, which applications are driving the highest value growth, and how regulatory shifts are redefining quality benchmarks. You will see where market concentration is building and where fragmentation offers agility. You will understand the interplay between acetone pricing, geopolitical supply disruptions, and the premium pricing of electronic-grade materials.
However, the full strategic value of this intelligence is realized only through access to the complete dataset, scenario analyses, and detailed regional and segment-level forecasts. The overview provided here is a preview of the analytical rigor and strategic relevance embedded in the full report. To secure your competitive advantage in 2026 and build a resilient, forward-looking strategy, we invite you to access the complete PW Consulting High-purity Isopropyl Alcohol Market report. The detailed intelligence within will empower your organization to make informed decisions on procurement, capacity planning, supplier qualification, and market entry, ensuring you are not just reacting to market changes, but anticipating and shaping them.
The high-purity IPA market is at a pivotal juncture. The convergence of semiconductor scaling, pharmaceutical innovation, and supply chain recalibration creates a landscape rich with opportunity for those equipped with the right intelligence. PW Consulting stands ready to provide the clarity and depth you need to lead in this dynamic market. Explore the full report to unlock the actionable insights that will drive your success.
High-purity Isopropyl Alcohol (IPA) Market
For detailed analysis of this topic, please visit the official page: High-purity Isopropyl Alcohol (IPA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
The China mobile substation market's revenue trajectory shows robust growth from USD 610 Million in 2020 to an expected USD 1,320 Million by 2035. The market demonstrates a consistent upward trend, bolstered by urbanization, grid investments, and greater renewable penetration. A sharp uplift in revenue is observed from 2025 onwards, following enhanced government spending on smart grid and resilience infrastructure projects.
Read More - https://bussinessinsights.com/research-report/china-mobile-substation-market
Utilities dominate the application share in the China mobile substation market for 2025, reflecting the sector’s need for fast and reliable energy deployment during maintenance, outages, or peak events. Renewable energy projects represent a fast-growing segment, given government targets for clean power integration. Industrial applications, including mining and oil & gas, also contribute substantially as demand for on-site, regenerative power rises in isolated regions.
Request Free Sample- https://bussinessinsights.com/request/semiconductor-and-electronics/china-mobile-substation-market
Frequently Asked Questions
Who are the key players in China Mobile Substation Market industry?
Top players in the China Mobile Substation Market include Siemens AG, ABB Ltd., Eaton Corporation, Schneider Electric SE, and TGOOD. These companies lead through their technological innovation, robust supply networks, extensive portfolios, and strong presence in the local and global power infrastructure markets.
What is the China Mobile Substation Market growth?
The China Mobile Substation Market is witnessing significant growth, driven by increasing infrastructure development and rapid urbanization. For example, in 2023, Siemens AG reported a surge in demand for mobile substations to support grid modernization and emergency backup solutions across China’s expanding cities and industrial zones.
Which segment accounted for the largest China Mobile Substation Market share?
The utilities segment holds the largest share in the China Mobile Substation Market. This dominance is due to growing investment in grid resilience and quick deployment requirements for temporary or emergency power supply within the utility sector, facilitating continuous electricity delivery during grid upgrades or disaster recovery.
Thanks & Regards,
priya
sales@bussinessinsights.com
PW Consulting Report: Trailer Refrigeration Market Hits $544.07 Million in 2025, Projected 5.67% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Cold Chain: Strategic Imperatives in the Trailer Refrigeration System Market (2026–2032)
The global supply chain stands at a critical inflection point. As logistics networks strive for greater resilience, efficiency, and environmental compliance, the trailer refrigeration system market has emerged as a vital enabler of modern cold chain integrity. From temperature-sensitive pharmaceuticals to perishable food shipments crossing continents, the reliability of transport refrigeration directly influences product safety, regulatory adherence, and commercial viability. PW Consulting's latest in-depth market analysis, Trailer Refrigeration System Market: Global Industry Outlook 2026–2032 , offers a comprehensive strategic roadmap for executives, investors, and supply chain leaders seeking to navigate this rapidly evolving landscape.
Trailer Refrigeration System Market
This report is engineered not merely as a statistical compendium, but as a decision-support instrument. Drawing on rigorous primary research, proprietary modeling, and granular competitive intelligence, the study quantifies market trajectories, dissects segment-level value drivers, and evaluates the operational and regulatory forces reshaping the industry. For organizations operating in 2026, when capital allocation, product roadmapping, and compliance strategy demand precision, this analysis delivers the contextual clarity needed to move beyond reactive tactics and toward sustained competitive advantage.
Market Trajectory: A Decade of Measured Expansion
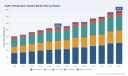
The historical trajectory of the trailer refrigeration system market reflects a sector characterized by steady organic growth, punctuated by technological modernization and regulatory evolution. Between 2020 and 2025, global revenue expanded from approximately 406.5 million USD to 544.1 million USD, demonstrating consistent demand absorption across developed and emerging logistics corridors. This upward momentum is projected to continue through the 2026–2032 forecast horizon, with the market expected to surpass 789.7 million USD by the close of the decade.
At the core of this expansion lies a compound annual growth rate of 5.67 percent, a figure that signals more than nominal market scaling. It indicates structural demand amplification driven by cold chain formalization, e-commerce fulfillment requirements, and the ongoing transition toward temperature-controlled freight solutions. For industry participants, this growth profile carries strategic weight: it suggests a market that is neither saturated nor speculative, but rather one where disciplined investment, product differentiation, and regional execution discipline can yield meaningful returns.
The forecast period also reveals nuanced dynamics that warrant executive attention. Growth is not uniform; it is being reshaped by shifting equipment preferences, ambient performance expectations, and the accelerating adoption of connected refrigeration platforms. Organizations that align their strategy with these underlying currents will be better positioned to capture share in a market where incremental operational efficiencies translate directly into margin preservation and customer retention.
Strategic Segmentation: Where Value Is Created and Captured
The report's segmentation framework is designed to illuminate how revenue flows through distinct equipment configurations, application verticals, and geographic corridors. Rather than treating the market as a monolith, the analysis isolates the structural factors that determine unit economics, competitive positioning, and long-term growth potential.
- Equipment Architecture: The market continues to be shaped by a diversified mix of power architectures, including electric, diesel, and hybrid configurations. Each pathway presents distinct trade-offs in total cost of ownership, emissions performance, grid dependency, and operational range. The analysis examines how fleet operators weigh these variables against deployment environments, regulatory exposure, and sustainability commitments, offering insight into where capital is naturally gravitating as infrastructure and policy conditions mature.
- Application End-Market Demand: Food and beverage logistics remain the dominant commercial driver, reflecting the scale and frequency of perishable goods movement. Simultaneously, pharmaceuticals and chemicals represent a high-value, compliance-intensive segment where temperature excursion risk carries disproportionate financial and reputational consequences. The report evaluates how these verticals differ in procurement behavior, service expectations, and receptivity to advanced monitoring and electric platform adoption.
- Regional Demand Patterns: Geographic distribution of demand is influenced by freight volume concentration, cold chain maturity, regulatory intensity, and local manufacturing or assembly ecosystems. The analysis maps how these factors intersect to create uneven but predictable growth pockets, helping stakeholders prioritize market-entry sequencing, service-network design, and partnership strategies without relying on blunt regional generalizations.
By contextualizing segmentation through an operational lens, the study equips readers to identify which sub-markets offer the most favorable risk-adjusted opportunities, where product specifications must evolve to meet segment-specific requirements, and how pricing architecture should adapt to preserve value across heterogeneous customer bases.
Road Transport Refrigeration Equipment Market
Competitive Dynamics: Incumbents, Innovation, and Consolidation Signals
Market structure analysis reveals a moderately concentrated landscape, with the top three participants collectively accounting for nearly half of total industry revenue and the leading five firms representing over 71 percent of market value. This concentration underscores the competitive advantage held by established players with scaled manufacturing capacity, broad service networks, and deep engineering heritage. Yet concentration alone does not dictate competitive outcomes; it intensifies the premium on differentiation, compliance readiness, and ecosystem integration.
Several core participants define the current competitive baseline. Carrier Transicold, headquartered in Charlotte, North Carolina, maintains a comprehensive portfolio spanning single-temperature and multi-temperature trailer refrigeration units, electric and stationary configurations, and heating platforms, reinforced by its ecoForward sustainability technologies. Thermo King, based in Woodridge, Illinois, competes with its Precedent trailer solutions, T-90 Series architecture, ConnectedSuite telematics capabilities, and TriPac auxiliary power units, while expanding its all-electric and e-reefer offerings with an emphasis on emissions-compliant performance. Polar King Mobile, operating from Fort Wayne, Indiana, has carved a distinct position with all-electric compact refrigerated trailers engineered for modular deployment, E-Track readiness, and NATM compliance, utilizing refrigeration systems capable of maintaining precise temperature bands across demanding transit conditions.
The competitive narrative is further shaped by recent product and regulatory milestones that illustrate how the market is evolving in real time. In early 2026, Utility Trailer Manufacturing Company and Cargobull North America introduced next-generation hybrid transport refrigeration units designed for enhanced cooling performance and efficiency within their 3000R refrigerated trailer lineup. Around the same period, Polar King previewed fresh trailer innovations at a major industry expo, signaling continued product iteration in the compact electric segment. These developments unfold against a backdrop of tightening regulatory architecture, including updated cold appliance emissions standards and refrigerant guidance that increasingly steer procurement decisions toward lower-global-warming-potential solutions and zero-emission transition pathways.
For corporate strategists, the implication is clear: competitive advantage in this market is increasingly determined by how effectively firms integrate regulatory foresight into product design, align service and telematics capabilities with fleet customer expectations, and communicate verifiable sustainability performance without sacrificing operational reliability.
Regulatory and Technological Currents Reshaping the Market
No strategic assessment of the trailer refrigeration system market is complete without a rigorous examination of the regulatory environment. Compliance is no longer a peripheral concern; it is becoming a primary determinant of equipment eligibility, total cost of ownership, and long-term asset viability. Over the past several years, regulators have steadily tightened emissions expectations for transport refrigeration units, with particular emphasis on refrigerant global warming potential thresholds, particulate emission controls, and registration and reporting obligations for owners and large facilities.
These regulatory pressures are compounded by evolving refrigerant chemistry and component standards. The industry's shift toward lower-GWP refrigerant blends reflects a broader transition toward systems that can meet compliance mandates without compromising cooling capacity or serviceability. At the same time, telematics and connected monitoring are transitioning from value-added features to operational necessities, enabling fleet managers to track temperature excursions, optimize preventive maintenance, and demonstrate compliance documentation with greater precision.
The interaction between regulation and technology creates a distinctive strategic environment. Equipment that meets current compliance thresholds may still face retrofit risk or shortened service life if future amendments tighten standards further. Conversely, platforms designed with forward-looking architecture can reduce transition costs, preserve resale value, and strengthen supplier credibility with compliance-sensitive customers. The report evaluates these dynamics in detail, helping organizations distinguish between compliance-driven costs and strategic investments that build durable market positioning.
What This Report Delivers for 2026 Decision-Makers
PW Consulting's market study is structured to convert complex industry data into actionable strategic intelligence. The analysis extends beyond high-level sizing to address the operational and commercial questions that executives face when allocating resources, evaluating competitive threats, and planning product or service expansion. Key deliverables include:
- Market sizing and forecast architecture that provides a transparent view of historical performance and projected growth pathways, enabling scenario planning around demand sensitivity, adoption pacing, and external shocks.
- Segment-level evaluation that isolates the structural drivers behind equipment type preferences, application-specific procurement patterns, and regional demand concentration, supporting more precise go-to-market and investment decisions.
- Competitive profiling that maps the strategic positioning, product offerings, and recent activity of leading participants, with context on how innovation, service capability, and compliance readiness influence share dynamics.
- Regulatory and technology impact assessment that connects emissions standards, refrigerant transitions, telematics adoption, and enforcement trends to practical procurement, design, and service implications.
- Strategic recommendation frameworks tailored to manufacturers, component suppliers, fleet operators, and investors, helping each audience translate market signals into prioritized actions for capacity planning, R&D focus, partnership strategy, and risk mitigation.
By integrating quantitative forecasts with qualitative market intelligence, the report enables readers to stress-test assumptions, identify where consensus expectations may understate or overstate opportunity, and build strategies that remain robust across a range of plausible futures.
Conclusion: Turning Market Intelligence into Strategic Action
The trailer refrigeration system market in 2026 is defined by a convergence of forces: durable cold chain demand, accelerating sustainability mandates, technological differentiation in electric and hybrid platforms, and a competitive field where scale and service quality remain powerful advantages. Growth projections indicate that the sector will continue expanding toward the high-700-million-USD range by 2032, but the more consequential question for decision-makers is not simply how large the market will become, but how value will be distributed across segments, regions, and competitive tiers.
Organizations that treat this market as a purely mechanical equipment category risk overlooking the strategic levers that determine long-term performance: compliance architecture, telematics-enabled service differentiation, segment-specific product customization, and disciplined regional execution. Those that approach it as a strategically layered ecosystem will be better positioned to protect margins, win compliance-sensitive contracts, and build defensible relationships with fleet customers who increasingly evaluate suppliers on total value rather than unit price alone.
This report provides the depth, structure, and forward-looking context required to make those judgments with confidence. To access the full dataset, detailed segmentation analysis, competitive benchmarking, and scenario-based strategic guidance, we invite executives and research buyers to visit the source page for the complete PW Consulting market intelligence package.
For detailed analysis of this topic, please visit the official page: Trailer Refrigeration System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Beauty Devices Market to Hit $176.36M by 2032, 11.54% CAGR Drives 2026-2032 Forecast
By PW Consulting, 2026-09-16
Navigating the Inflection Point: Strategic Intelligence for the 2026 Beauty Devices Market
The global beauty devices market stands at a decisive inflection point. After a period of contraction that tested supply chains, compressed margins, and forced a hard reset in consumer expectations, the industry is now preparing for a sustained, technology-led expansion. For executives, investors, and product leaders operating in 2026, the question is no longer whether the category will rebound, but how to position across the right segments, geographies, and regulatory pathways before the next wave of competition compresses differentiation.
This introduction frames the strategic rationale behind our latest Beauty Devices Market research. The full study is designed to convert macroeconomic signals into executable decision frameworks. What follows is a preview of the analytical architecture, the competitive terrain we map, and the market dynamics that will shape portfolio strategy in the years ahead.
The Trajectory: A Contraction That Forged Discipline, and a Forecast Built for Scale
The historical record tells a story of correction. Between 2020 and 2025, the market navigated a demanding cycle, with revenue compressing through the post-pandemic recalibration period before stabilizing into a new baseline. That contraction was not merely a temporary dip; it functioned as a market-wide stress test. It separated durable innovation from short-lived novelty, exposed fragile channel strategies, and reshaped how consumers evaluate efficacy, safety, and long-term value in at-home and professional treatment devices.
From that reset, the forward outlook is notably constructive. The market is projected to grow from an estimated 88.56 million USD in 2026 to approximately 176.36 million USD by 2032, supported by a forecasted compound annual growth rate of 11.54 percent across the 2026 to 2032 period. This trajectory reflects more than top-line recovery. It signals structural momentum driven by converging forces: the maturation of home-use aesthetics, escalating demand for non-invasive and minimally invasive modalities, and the steady integration of intelligent diagnostics into both consumer and professional devices.
Beauty Devices Market
For leadership teams, the strategic implication is clear. Planning in 2026 cannot rely on category-level optimism alone. It requires a granular understanding of which subsegments are absorbing investment, which use cases are expanding fastest, and where regional adoption curves are diverging. The full report is built to provide that clarity without forcing executives to extrapolate from surface-level headlines.
What the Study Delivers: Operational Intelligence Over Generic Narrative
A market overview can confirm direction. It cannot, on its own, guide capital allocation, channel construction, or product roadmap choices. Our research is structured to bridge that gap. The study moves beyond high-level trend commentary to deliver a decision-ready architecture that organizations can plug directly into strategy sessions, board discussions, and annual planning cycles.
The report combines macro market modeling with segmentation frameworks that dissect the landscape across device categories, end-use environments, and geographic markets. Rather than presenting static snapshots, the analysis is designed to help leaders pressure-test assumptions. It connects historical volatility to forward-looking scenarios, allowing readers to evaluate how shifts in consumer behavior, clinical adoption, and distribution models could alter growth outcomes across the forecast horizon.
Equally important, the study treats the beauty devices ecosystem as a competitive system rather than a collection of isolated product lines. It examines how technology roadmaps, brand positioning, and regulatory milestones interact to shape market access. The intent is to give executives a working map of where differentiation is still achievable, where consolidation pressure is building, and where emerging standards may redefine what counts as a defensible product proposition.
Competitive Architecture: Incumbents, Specialists, and the Reconfiguration of Advantage
The competitive field in beauty devices is defined by a blend of global personal care and electronics incumbents, focused aesthetic technology specialists, and a growing set of clinically oriented entrants pursuing regulatory validation as a moat. Market concentration remains moderately distributed, with the top three players accounting for roughly 24.6 percent of market share and the top five reaching approximately 32.0 percent. That concentration profile matters strategically: it suggests the category is large enough to support multiple viable positions, but competitive enough that differentiation must be engineered deliberately rather than assumed.
Several established names illustrate the diverse strategic postures now competing for share. L'Oréal S.A., based in Clichy, France, has extended its portfolio into AI-driven skin analysis and nano-resurfacing through devices such as Perso, Lumea, and Cell BioPrint. Philips, headquartered in Amsterdam, Netherlands, has built recognition around adaptive tone recognition within its hair removal and skincare device lines. FOREO, from Stockholm, Sweden, has advanced its Luna series of microcurrent and LED facial devices while pairing product development with AI-powered skin analysis and circular economy programs.
Alongside these consumer-facing ecosystems, a parallel competitive dynamic is unfolding in professional and hybrid aesthetic platforms. InMode Ltd., in Irvine, California, develops radiofrequency-based aesthetic platforms for facial and body treatments. Sofwave Medical, based in San Clemente, California, supplies SUPERB ultrasound devices for non-invasive skin lifting and toning. Cutera, Inc., in Brisbane, California, produces laser and RF systems spanning skin rejuvenation, hair removal, and vascular treatments. NuFACE, part of the Carol Cole Company in Vista, California, focuses on microcurrent facial toning devices for non-invasive anti-aging applications. CLASSYS Inc., in Seoul, South Korea, offers radiofrequency-based medical aesthetic platforms such as Volnewmer, including CE MDR certification. Dermalogica, Alma Lasers, Accure Acne, Inc., and SkinHealth Systems further widen the competitive spectrum, each pursuing a distinct blend of clinical credibility, treatment specificity, and channel alignment.
This is not a market where scale alone guarantees advantage. The strategic edge increasingly comes from how well a company connects device performance, user experience, evidence generation, and regulatory readiness. The full report evaluates these players through that operational lens, tracing how their technology choices, launch cadence, and certification activity position them relative to the next generation of entrants and the shifting expectations of both professional and home users.
Aesthetic Devices Market
Regulatory Momentum and Technology Signals as Strategic Variables
One of the most consequential dynamics for 2026 planning is the accelerating cadence of regulatory and technology milestones. In this category, clearance and certification activity is not simply a compliance event; it often functions as a market-access trigger, a credibility signal, and at times a competitive barrier. The study tracks these developments as strategic inputs rather than background news.
Recent regulatory progress illustrates the point. Accure Acne, Inc. secured FDA clearance for its laser system for the long-term treatment of mild to severe inflammatory acne vulgaris. CLASSYS received CE MDR approval for its Volnewmer radiofrequency-based anti-aging system, a notable milestone as the first radiofrequency aesthetic device to achieve that designation in Europe. Ultherapy PRIME obtained FDA clearance for use on the abdomen and arms with real-time visualization across face, neck, décolleté, and body applications. Cutera's truFlex clearance expanded into rehabilitation and therapy applications. In parallel, Dermalogica's PRO Pen microneedling system secured FDA clearance, with launch planned in the US in 2026.
These events are not isolated. They reflect a broader pattern in which regulatory validation, device precision, and treatment specificity are increasingly intertwined. For companies operating in or entering the market, this creates a dual strategic question: how to build products that meet clinical and consumer expectations, and how to navigate a landscape where approvals, certifications, and evidence standards can alter the pace of adoption in specific segments. The report integrates these dynamics into its forward analysis so that leadership teams can better anticipate where access, messaging, and investment priority should shift.
Why This Research Matters for 2026 Decision-Making
The beauty devices market in 2026 rewards disciplined strategy over broad positioning. Organizations that succeed will be those able to align product development with validated demand, construct channel strategies that reflect regional and application-level realities, and interpret regulatory signals as part of competitive planning rather than as a separate compliance track.
This study is designed to support exactly that kind of decision-making. It provides the structural context needed to evaluate where growth is likely to concentrate, how the competitive field is rearranging itself, and which strategic levers will matter most as the forecast period unfolds. By connecting historical volatility to a forward CAGR of 11.54 percent and a projected 2032 revenue trajectory of roughly 176.36 million USD, the research frames the market as both a recovery story and a reallocation story. In other words, the real strategic task is not simply to capture growth, but to capture the right growth.
The full report goes further. It delivers the segmentation detail, company-level analysis, and market-structure insight necessary to translate high-level momentum into actionable plans. For executives evaluating expansion, product roadmap priorities, partnership strategy, or market-entry timing, the complete analysis is built to reduce uncertainty and sharpen judgment.
Conclusion: From Category Outlook to Executable Strategy
The beauty devices sector is entering a phase in which insight quality will separate durable players from reactive ones. The market's path from contraction to expansion is now backed by a credible growth trajectory, but realizing that opportunity will depend on how precisely organizations can read the subsegments, competitive moves, and regulatory developments shaping the landscape. This research begins with that premise and is structured to help leaders act on it.
To access the complete segmentation framework, competitive assessment, and forward-looking scenario analysis, we invite you to explore the full Beauty Devices Market research. The detailed intelligence within is intended to serve as a working resource for 2026 planning and beyond.
For detailed analysis of this topic, please visit the official page: Beauty Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Blade Fuse Market to Reach $1.96B by 2032, CAGR 5.8%
By PW Consulting, 2026-09-16
Navigating the Automotive Blade Fuse Market: Strategic Intelligence for 2026 Decision-Making
The automotive electrical ecosystem is undergoing a structural transformation driven by electrification, advanced driver-assistance systems, and increasingly complex in-vehicle power architectures. At the foundation of these circuits lies a critical yet often overlooked component: the automotive blade fuse. As vehicle manufacturers and aftermarket suppliers navigate tightening reliability standards, fluctuating raw material costs, and shifting regional demand patterns, the need for precise, forward-looking market intelligence has never been more acute. Our latest Automotive Blade Fuse Market research delivers exactly that, translating historical trajectories and multi-year projections into actionable strategic frameworks for 2026 and beyond.
This analysis is designed specifically for executives, procurement leaders, product planners, and competitive intelligence teams who require more than headline figures. The study anchors its methodology in verified historical data spanning 2020 through 2025, then extends the analytical lens across a forecast period from 2026 to 2032. Over the historical window, the market demonstrated steady expansion, moving from approximately 0.99 billion USD in 2020 to 1.31 billion USD by 2025. The trajectory continues into the forecast horizon, with 2026 projections reaching 1.43 billion USD and sustained growth anticipated through 2032, when the market is expected to approach 1.96 billion USD. These figures reflect a compound annual growth rate of 5.8 percent, a pace that signals consistent demand expansion rather than speculative volatility.
Such macro-level momentum creates both opportunity and complexity. Growth is not uniformly distributed across product categories, application segments, or geographic corridors. Manufacturers must understand how pricing dynamics, regulatory compliance, supply chain localization, and vehicle architecture shifts interact to shape revenue pools. Our report dissects these intersections without overwhelming readers with fragmented statistics, instead presenting a structured narrative that clarifies where strategic focus will yield the highest return on investment.
What the Research Delivers: Operational Intelligence for Product, Pricing, and Portfolio Strategy
A market study is only as valuable as its applicability to real-world decision cycles. This report is built around operational utility. It moves beyond generic industry commentary to provide structured assessments that can be integrated directly into annual planning, sourcing evaluations, and competitive positioning exercises. Readers will encounter detailed evaluations of product architecture trends, including the continued dominance of blade-style configurations in contemporary vehicle electrical designs, alongside comparative insights into glass tube and other specialized fuse formats. The analysis examines how form factor preferences align with OEM specifications, aftermarket replacement cycles, and regional certification requirements.
The research also maps the evolution of application-driven demand. Passenger vehicle platforms remain the primary consumption base, reflecting high production volumes and extensive electrical component integration. Commercial vehicle segments introduce distinct load profiles, environmental durability expectations, and maintenance intervals that influence fuse selection and procurement frequency. Other application corridors, including specialty mobility platforms and emerging aftermarket service networks, are evaluated for their incremental contribution to overall market expansion. By contextualizing these segments within broader vehicle production forecasts and fleet turnover cycles, the study enables stakeholders to anticipate demand shifts rather than react to them.
Pricing architecture and value chain dynamics receive equal attention. The report explores how automotive-grade manufacturing standards, testing protocols, and certification pathways influence cost structures and competitive positioning. It examines the interplay between volume-driven OEM supply agreements and the margin characteristics of aftermarket distribution, highlighting how players optimize portfolio mix to balance volume stability with profitability. Supply chain considerations are addressed through the lens of component sourcing, production capacity allocation, and the increasing importance of regional supply resilience.
Forecasting methodology is transparent and grounded in observable industry indicators. Projections integrate historical growth patterns, vehicle production outlooks, electrification roadmaps, and regulatory trajectories to construct a multi-scenario view of market development. This approach allows decision-makers to stress-test internal assumptions against external baselines, reducing exposure to overconfidence or missed inflection points.
Competitive Landscape: Concentration, Positioning, and Strategic Differentiation
Market structure plays a decisive role in pricing power, innovation pacing, and customer access. The automotive blade fuse sector exhibits meaningful concentration, with a compact group of established manufacturers capturing a substantial share of global demand. The report profiles the companies that define this landscape, analyzing their geographic footprints, product specializations, certification capabilities, and go-to-market strategies.
Littelfuse, Inc., headquartered in Rosemont, Illinois, operates as a broad-line manufacturer of automotive blade fuses and related circuit protection products, serving both OEM and aftermarket channels with a focus on standardized reliability and integrated protection solutions. Eaton Corporation, based in Cleveland, Ohio, leverages its Bussmann series to deliver blade fuse offerings tailored for automotive and marine overcurrent protection, combining engineering heritage with extensive distribution networks. Mersen S.A., headquartered in Courbevoie, France, supplies automotive fuses including blade types, positioning itself within electrical protection portfolios that emphasize material performance and application-specific engineering.
Beyond North America and Western Europe, the competitive field includes highly specialized manufacturers with strong regional anchors and global supply relationships. Pacific Engineering Corporation (PEC), located in Ogaki, Gifu, Japan, manufactures automotive blade fuses supplied to global vehicle makers, underscoring the importance of precision manufacturing and long-term OEM collaboration. MTA SpA, based in Codogno, Italy, produces certified automotive blade fuses and power distribution components, aligning product quality with rigorous automotive certification expectations. Conquer Electronics Co., Ltd., in New Taipei City, Taiwan, operates as a designer and manufacturer of automotive and other fuses including blade types, reflecting the role of flexible manufacturing and export-oriented production in the broader supply ecosystem.
European specialist producers further diversify the landscape. ESKA Erich Schweizer GmbH, headquartered in Kassel, Germany, produces miniature and automotive fuses including blade designs, emphasizing compact form factors and application-sensitive engineering. SIBA, based in Lünen, Germany, manufactures high-quality fuses for automotive and industrial applications, reinforcing the market's emphasis on durability and compliance. AEM Components (USA), Inc., located in San Diego, California, supplies automotive-grade surface mount and blade fuses, addressing niche requirements that span conventional and advanced electrical architectures.
Thermal Fuse Market
The report evaluates how these players compete across dimensions that matter most to procurement and strategy teams: certification breadth, production scalability, OEM relationship depth, aftermarket penetration, and responsiveness to regional specification variations. It also examines the structural implications of market concentration, where a limited number of large suppliers shape baseline pricing expectations and technology adoption rhythms. Understanding this concentration is essential for identifying negotiation leverage, assessing entry barriers, and evaluating partnership or sourcing diversification strategies.
Industry Dynamics Shaping 2026 and the Forecast Horizon
No market develops in isolation. The automotive blade fuse sector is influenced by overlapping forces that alter demand timing, product requirements, and supplier competitiveness. Vehicle electrification continues to redefine electrical load characteristics, increasing the importance of reliable circuit protection across hybrid, battery-electric, and conventionally powered platforms. At the same time, the proliferation of electronic control units, connectivity modules, and advanced sensors expands the number of protected circuits within a single vehicle, changing fuse density requirements and replacement patterns.
Regulatory and safety expectations further tighten the operational environment. Automotive-grade certification, thermal performance validation, and environmental durability standards influence both product design and supplier qualification processes. These requirements create meaningful differentiation between general-purpose and certified automotive offerings, affecting how manufacturers structure their portfolios and how buyers evaluate total cost of ownership.
Supply chain configuration is another critical dynamic. Regional production footprints, logistics resilience, and material availability shape lead times and cost predictability. As manufacturers and Tier-1 suppliers increasingly prioritize supply security, the ability to source from trusted, certified producers with stable capacity becomes a strategic advantage rather than a tactical preference. The report places these dynamics in context, showing how they interact with demand growth to influence market outcomes over the 2026 to 2032 window.
Automotive Blade Fuse Market
Aftermarket behavior also remains a steady demand engine. Vehicle fleet aging, service interval patterns, and the replacement of legacy electrical components sustain consumption even as new vehicle architectures evolve. The interplay between OEM volume cycles and aftermarket replacement demand creates a multi-layered market rhythm that rewards companies capable of balancing both channels effectively.
Why This Research Matters for 2026 Strategy
The strategic value of this study lies in its ability to convert market complexity into structured decision support. For product planning teams, it clarifies where blade fuse demand is most likely to intensify and how application requirements are shifting. For procurement and sourcing leaders, it provides context on concentration, certification, and supply chain resilience that can inform supplier evaluation and contract negotiation. For competitive strategy groups, it outlines how established players position themselves and where differentiation opportunities may emerge.
Most importantly, the report is designed to prevent strategic overreach. Market growth at a 5.8 percent CAGR is meaningful, but it does not eliminate risk. Regional variation, application segmentation, and competitive concentration mean that aggregate growth can mask divergence at the segment level. Companies that rely on headline numbers alone may misallocate resources or underestimate the operational requirements needed to capture demand in specific corridors. By integrating historical performance, forward-looking projections, and competitive context, this research equips stakeholders to make calibrated decisions rather than assumptions.
The complete study expands on every dimension introduced here, offering detailed market sizing across historical and forecast periods, segmentation analysis that identifies where growth concentrates, competitive profiling that maps supplier strengths and positioning, and strategic implications tailored to product, pricing, and sourcing decisions. It is built for teams that require a rigorous baseline before committing capital, capacity, or commercial strategy.
For executives planning 2026 initiatives, the strategic question is no longer whether the automotive blade fuse market is expanding, but how to position within that expansion with precision. This report provides the analytical foundation to answer that question with confidence, while the full dataset and segment-level intelligence remain available for teams that need to ground strategy in complete, validated market intelligence.
For detailed analysis of this topic, please visit the official page: Automotive Blade Fuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Well Completion Equipment Market to Reach $18.5B by 2032, Growing at 5.13% CAGR
By PW Consulting, 2026-09-16
Navigating the Next Wave: Strategic Insights into the Well Completion Equipment Market Through 2032
The global energy landscape is entering a phase of calculated expansion, where efficiency, compliance, and technological resilience dictate competitive advantage. For operators, service providers, and investors, the well completion equipment market represents more than a transactional supply chain. It is a critical inflection point where geological complexity, regulatory evolution, and engineering innovation converge. As we move deeper into the 2026 decision cycle, understanding the structural drivers, competitive tensions, and material constraints shaping this sector is no longer optional. It is foundational to capital allocation, portfolio optimization, and long-term operational readiness.
Our latest market research on well completion equipment delivers a comprehensive, forward-looking assessment designed specifically for strategic planners and senior leadership teams. Spanning historical performance from 2020 through 2025 and projecting market trajectories through 2032, this study maps the revenue architecture, equipment specialization, application distribution, and regional footprint of a market that has consistently demonstrated resilience amid volatility. The analysis is structured to cut through noise, isolate actionable intelligence, and provide decision-makers with the clarity required to navigate an increasingly fragmented and regulation-intensive operating environment.
Market Architecture: Scale, Trajectory, and Structural Shifts
The well completion equipment market has evolved from a cyclical procurement category into a strategically calibrated segment of the broader oilfield services ecosystem. Over the past half-decade, revenue progression has reflected a combination of disciplined operator spending, accelerated unconventional development, and the gradual integration of intelligent completion technologies. The market closed the historical baseline year at approximately 12.22 billion USD, building on a compound annual growth trajectory that signals sustained demand across multiple development phases. Looking ahead to the 2026-2032 forecast window, the sector is projected to expand at a measured yet consistent compound annual growth rate of 5.13 percent, ultimately reaching an estimated 18.54 billion USD by the end of the forecast period.
This growth profile is not uniform. It is shaped by shifting capital priorities, the maturation of certain shale plays, and the steady push toward higher-pressure, higher-temperature well architectures in both established and emerging basins. The revenue curve reflects periods of consolidation, selective capacity expansion, and the gradual reallocation of expenditure toward completion systems that deliver longer operational lifecycles, improved zonal isolation, and greater conformance with evolving emissions standards. For corporate strategists, these patterns underscore a central reality: the market is rewarding suppliers and operators who can align equipment selection with long-term well performance rather than short-term cost minimization.
The study contextualizes these macro trends within a highly concentrated competitive environment. Market leadership is distributed across a handful of dominant players, with the top three firms collectively accounting for nearly half of total industry revenue and the top five firms capturing approximately two-thirds of the market. This concentration reflects the technical barriers to entry, the capital intensity of advanced manufacturing, and the entrenched relationships between equipment manufacturers and major operating companies. Yet concentration does not equate to homogeneity. The report dissects how differentiated product portfolios, regional service capabilities, and technology roadmaps are reshaping competitive positioning across equipment categories and application domains.
Equipment Specialization and Application Dynamics
Well completion equipment is not a monolithic category. It is a portfolio of specialized tools, each tied to distinct operational objectives, reservoir conditions, and completion philosophies. The research provides a granular breakdown of the principal equipment segments that define market structure, examining how demand patterns differ across packers, sand control tools, multi-stage fracturing equipment, liner hangers, and valve systems. Rather than presenting static share figures, the analysis focuses on the functional drivers that determine segment growth, including reservoir complexity, well architecture design, and the increasing reliance on staged completion methodologies in horizontal and extended-reach wells.
Packers continue to anchor the equipment landscape, serving as the foundation for zonal isolation, pressure management, and intervention readiness. Their performance characteristics directly influence well integrity, production optimization, and long-term asset reliability. Sand control tools remain critical in formations where particulate production threatens operational continuity, driving sustained demand for advanced filtering, gravel packing, and hybrid completion approaches. Multi-stage fracturing tools have gained structural importance as operators pursue higher recovery factors through precise stimulation sequencing, while liner hangers and valve systems support the mechanical and flow-control architecture that underpins safe, efficient well completion.
Application-side analysis further clarifies how completion strategies diverge across operating environments. Onshore development continues to represent the dominant demand center, reflecting the scale of unconventional resource development, the prevalence of horizontal drilling programs, and the ongoing optimization of mature fields. Offshore operations, while representing a smaller share of total activity, carry disproportionate strategic weight due to higher technical complexity, stricter safety and environmental standards, and the growing deployment of subsea completion architectures. The report examines how these application profiles shape procurement cycles, service expectations, and technology adoption curves, providing operators and suppliers with a clearer view of where demand is most durable and where performance differentiation matters most.
Competitive Landscape and Strategic Positioning
The competitive dynamics of the well completion equipment market are defined by a blend of global scale, technical specialization, and targeted regional expansion. Leading participants operate across a spectrum of service models, from integrated completion offerings to focused manufacturing of high-performance tools. The study profiles the core companies shaping market direction, analyzing their strategic footprint, product capabilities, and recent operational developments that signal shifting priorities.
Major integrated service organizations maintain a central role through broad equipment portfolios, proprietary completion technologies, and extensive field support networks. Their strategies increasingly emphasize intelligent completion systems, flow control solutions, and subsurface safety architectures that align with operator demands for real-time monitoring, improved well control, and extended intervention intervals. Alongside these broader service providers, specialized manufacturers and completion-focused firms contribute critical technological niches. Their product lines often target specific operational challenges, including high-pressure and high-temperature environments, multistage horizontal completions, expandable isolation technologies, and advanced sleeve systems designed for precision fracturing sequences.
Recent corporate activity highlights the pace of strategic adaptation within the sector. Expansion into international markets, targeted product launches, and the introduction of specialty systems for demanding well conditions all point to a competitive environment where differentiation is increasingly tied to engineering capability and geographic responsiveness. The report integrates these developments into a broader competitive assessment, examining how recent launches, delivery milestones, and portfolio broadening initiatives influence market positioning. By tracking these movements, the analysis provides a practical framework for evaluating which companies are strengthening their foothold in core segments, which are extending into adjacent application areas, and where partnership or procurement opportunities may emerge.
Worldwide Intelligent Well Completion Market
Regulatory Pressures, Material Constraints, and Operational Realities
Strategic planning in the well completion equipment market cannot be separated from the regulatory and material conditions that shape procurement decisions. Over the past year, the operating environment has been influenced by updated emissions requirements, revised performance standards, and shifting raw material cost dynamics. These factors do not merely affect compliance costs. They influence equipment specifications, design priorities, and the economic calculus behind technology selection.
Regulatory developments have placed renewed emphasis on reduced-emission completion practices and tighter performance expectations for hydraulically fractured wells. Updated federal guidance and extended performance standards have required operators to align completion workflows with broader environmental objectives, reinforcing the importance of equipment that supports emissions management, pressure control, and well integrity verification. At the same time, industry standards continue to serve as a baseline for equipment validation, ensuring that critical components such as subsurface safety valves and packers meet established requirements for personnel protection, environmental safeguarding, and asset reliability. The research maps these regulatory and standards-driven considerations into practical implications for equipment procurement, service planning, and long-term compliance strategy.
On the supply side, material cost dynamics have introduced a notable restraint in certain equipment categories. Fluctuations in metal pricing, influenced by global oversupply conditions, have affected input costs for components used in completion tools and packer manufacturing. While these cost pressures are not uniform across all product lines, they highlight the vulnerability of equipment economics to commodity market cycles and procurement timing. The study addresses these influences not as isolated headwinds, but as structural variables that affect pricing strategy, inventory planning, and supplier negotiations. By placing material constraints within the broader market context, the analysis equips decision-makers with a more realistic assessment of cost trajectories and procurement risk.
Well Completion Equipment Market
What the Report Delivers: An Executive Toolkit for 2026 Decisions
This market research is designed as an operational decision-support asset, not a passive overview. It translates broad market movement into a structured intelligence framework that can be applied to budgeting, procurement strategy, technology evaluation, and competitive benchmarking. The report integrates historical performance data, forecast modeling, segmentation analysis, competitive profiling, and market-structure indicators into a single coherent narrative. Its objective is to give executives and planning teams a clearer view of where demand is building, which equipment categories are gaining functional relevance, and how regulatory and material conditions are reshaping the cost and performance equations.
Readers will find detailed segmentation analysis that clarifies how equipment categories and application environments diverge in demand behavior, without reducing the market to simplistic share rankings. The study also examines regional demand patterns, mapping the distribution of activity across major geographic zones to highlight where market intensity is concentrated and where growth opportunities may develop. Competitive profiling extends beyond corporate descriptions, placing each key participant within the context of product focus, recent strategic moves, and market influence. This approach allows users to assess not only who leads today, but how competitive dynamics are likely to evolve as technology adoption, regulatory compliance, and regional expansion continue to reshape the field.
Importantly, the report is structured to support scenario-based planning. Forecast data, market concentration metrics, and equipment-level trends are presented in a way that allows leadership teams to test assumptions about capital deployment, supplier selection, and technology investment. Whether the priority is optimizing completion efficiency, managing compliance exposure, or identifying suppliers with proven capability in demanding well environments, the research provides the contextual foundation needed to make informed, forward-looking decisions.
Conclusion: Positioning for Durable Advantage
The well completion equipment market is entering a period where performance, compliance, and strategic agility will separate resilient organizations from those reacting to short-term cycles. With a forecast trajectory extending through 2032, a concentrated competitive landscape, and evolving regulatory and material conditions, the sector rewards those who can read structural signals early and align equipment strategy with long-term operational goals. This research study is built to support that objective. It offers a disciplined, data-grounded perspective on market scale, segmentation, competitive dynamics, and the external forces shaping procurement and technology choices.
For leadership teams preparing 2026 capital plans, supplier evaluations, and completion strategy reviews, the report delivers the analytical depth required to move beyond surface-level market narratives. Detailed segmentation breakdowns, equipment-level demand drivers, regional activity patterns, and full competitive profiling are available in the complete study. Explore the full market intelligence framework to access the precise data, forecasts, and strategic assessments needed to guide your next decisions with confidence.
For detailed analysis of this topic, please visit the official page: Well Completion Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blockchain Finance Market to Hit $126.88B by 2032, Growing at 26.94% CAGR
By PW Consulting, 2026-09-16
Blockchain Finance Market: Strategic Intelligence for the 2026 Enterprise
The convergence of traditional finance and distributed ledger technology has crossed a critical threshold. What began as experimental pilots and niche cryptocurrency transactions has evolved into a structured financial infrastructure supporting regulated assets, institutional settlements, and enterprise-grade tokenization. For corporate strategists, treasury leaders, and investors navigating the 2026 landscape, understanding the trajectory of the blockchain finance market is no longer optional. It is a prerequisite for capital allocation, risk management, and competitive positioning.
PW Consulting's latest comprehensive market research delivers the analytical rigor required to make informed decisions in this rapidly maturing sector. This report synthesizes historical performance, forward-looking projections, structural segmentation, and competitive intelligence into a single strategic framework. Below, we outline the market's current trajectory, the operational realities shaping deployment, and the regulatory architecture that will define execution over the next several years.
Macro Trajectory and the Investment Horizon
The blockchain finance market has demonstrated sustained expansion across the historical evaluation window, accelerating from foundational levels in the early 2020s to a materially larger operational footprint by 2025. Our tracking of revenue generation across the sector shows a consistent upward curve, with the market surpassing multiple inflection points as institutional participation deepened and tokenized asset infrastructure matured.
Looking ahead through the 2026–2032 forecast horizon, the market is projected to follow a steep growth trajectory, reflecting compounding adoption across payment networks, capital market tokenization, and decentralized financial infrastructure. The compound annual growth rate encoded in our baseline forecast underscores the velocity at which blockchain-native financial services are scaling relative to conventional analogues. This is not a speculative curve. It is a projection anchored in adoption patterns, regulatory clarity, and the structural migration of financial workflows onto distributed platforms.
For enterprise decision-makers, this trajectory carries two immediate implications. First, the window for establishing competitive presence in high-growth segments is narrowing as infrastructure providers consolidate market share. Second, the revenue potential embedded across transaction rails, asset management, and cross-border settlement warrants serious evaluation against internal digital transformation roadmaps and liquidity strategy. Organizations that map their capabilities to the segments experiencing the strongest tailwinds will be better positioned to capture disproportionate share as the market expands toward the decade's end.
Structural Segmentation and Operational Realities
Blockchain finance does not grow as a monolith. Deployment patterns, transaction volumes, and protocol preferences vary significantly across use cases, geographies, and technical architectures. Our report dissects these structural layers to help leaders isolate the opportunities most relevant to their strategic mandate.
Transaction Types and Capital Flows
Payment and settlement activity continues to dominate transaction volume, with peer-to-peer transfers and cross-border payment solutions capturing substantial portions of market activity. Cryptocurrency lending and supply chain finance represent adjacent but structurally distinct categories, each requiring specialized risk frameworks, counterparty diligence, and regulatory compliance postures. The distribution of transaction types reflects where blockchain delivers the clearest operational advantages: speed of settlement, reduced intermediary friction, and programmable financial logic.
Protocol Ecosystems and Infrastructure Choices
The protocol landscape reveals a clear hierarchy of adoption. Bitcoin remains the most extensively utilized network by transaction volume within the broader market, while Ethereum continues to anchor a significant portion of tokenized asset activity and decentralized financial applications. Enterprise-oriented frameworks, including Hyperledger and Ripple, serve specialized institutional use cases where permissioned structures, interoperability requirements, and regulatory alignment take precedence over open public-network deployment. Understanding the protocol mix is essential for technology procurement, risk assessment, and long-term infrastructure planning.
Application Domains and Enterprise Deployment
Digital asset management stands as the largest application category, reflecting the institutional demand for custody, portfolio infrastructure, and asset servicing across both native digital assets and tokenized representations of traditional instruments. Trade finance and digital identity solutions constitute meaningful secondary pillars, each addressing structural inefficiencies in legacy processes. The breadth of application adoption signals that blockchain finance is no longer confined to speculative trading environments. It is being embedded into core financial operations where transparency, auditability, and settlement certainty carry measurable commercial value.
Geographic Distribution and Regional Dynamics
Market activity spans multiple regions, with mature financial centers in North America and Europe maintaining substantial share alongside rapidly expanding activity across Asia Pacific. Emerging regions, including Latin America and the Middle East and Africa, represent smaller but strategically important footholds where blockchain-based financial services address specific gaps in legacy infrastructure, cross-border liquidity, and financial inclusion. Regional divergence in regulatory posture, banking integration, and technology adoption creates distinct entry strategies for organizations evaluating geographic expansion.
Competitive Landscape: Positioning Among Core Players
The competitive environment in blockchain finance is defined by a blend of incumbent financial institutions extending into digital infrastructure, technology-native platforms building capital market utilities, and payment networks scaling institutional settlement capabilities. Our report profiles the dominant participants shaping the market's architecture and outlines the strategic moves that are redefining competitive boundaries.
Societe Generale-FORGE has established a focused presence in regulated digital asset issuance, leveraging public blockchain networks for the deployment of stablecoin instruments backed by institutional custody arrangements. Their approach illustrates how traditional banking entities are bridging balance-sheet credibility with blockchain execution layers, a model that carries relevance for organizations evaluating partnership structures and regulated digital currency infrastructure.
Figure Technology Solutions operates as a blockchain-native capital marketplace designed for the origination, funding, and trading of tokenized assets and real-world assets. By constructing an end-to-end marketplace around asset tokenization, the company addresses a structural need for liquidity, distribution, and secondary market functionality that traditional infrastructure has struggled to deliver at scale. Their trajectory reflects the broader institutional push toward asset digitization as a capital markets modernization strategy.
DeFi Technologies bridges traditional capital markets and decentralized finance through financial technology platforms that integrate exchange-traded product structures and treasury solutions. Their positioning highlights a growing intersection where institutional investors seek regulated exposure to digital asset ecosystems without abandoning familiar investment wrappers. This convergence plays an important role in broadening access and establishing institutional-grade entry points into decentralized financial markets.
Ripple continues to anchor its strategy around cross-border payment networks and institutional banking solutions built on its underlying ledger infrastructure. The company's emphasis on settlement efficiency and institutional interoperability positions it as a key participant in the enterprise payment and liquidity management segment, where transaction speed and counterparty trust remain decisive factors.
Recent developments among these and adjacent market participants reinforce the pace of structural change. The launch of regulated stablecoin instruments on public blockchains with institutional reserve custodians, the authorization of major post-trade infrastructure providers to offer tokenization services, and the emergence of public companies natively issuing equity instruments on blockchain all point toward the normalization of digital asset workflows within regulated financial ecosystems. These milestones are not isolated experimentations. They represent compounding steps toward a reconfigured financial infrastructure.
Regulatory Architecture and Market Dynamics
Regulatory evolution is the single most powerful force shaping blockchain finance deployment in 2026. For years, market participants navigated fragmented guidance and jurisdictional uncertainty. That environment is now being replaced by defined frameworks that establish boundaries for stablecoin issuance, securities classification, and crypto-asset service provision.
In the United States, the establishment of a federal regulatory framework for stablecoins marked a foundational shift, providing clearer operating parameters for issuers and users of regulated digital currency instruments. Subsequent regulatory clarifications addressing the application of federal securities laws to crypto assets and transactions have further reduced ambiguity for institutional participants seeking to structure compliant offerings. These developments do not eliminate risk, but they convert an environment of uncertainty into one where compliance strategy can be designed with greater precision.
Across the Atlantic, the Markets in Crypto-Assets regulation has entered its full application phase, representing the first comprehensive regulatory framework for crypto-assets at scale. Its technical standards and service provider requirements create a structured operating environment that influences not only European market participants but also global organizations seeking to align their product design and compliance infrastructure with internationally recognized standards. The Bank for International Settlements has recognized this framework's significance, reinforcing its role as a reference point for cross-border regulatory coordination.
Blockchain Finance Market
These regulatory developments carry direct operational consequences. Organizations entering blockchain finance markets must now account for licensing pathways, reserve and custody requirements, disclosure obligations, and jurisdictional variance in treatment of digital assets. The market's growth trajectory will increasingly favor participants that integrate regulatory foresight into product design rather than treating compliance as a downstream constraint. Strategic advantage will accrue to those who can align innovation with demonstrable regulatory legitimacy.
Strategic Implications for 2026 Decision-Making
The data and dynamics captured in this research translate into several actionable strategic considerations for enterprise leaders evaluating blockchain finance in 2026.
Worldwide Blockchain Insurance Market
- Asset and liquidity strategy: The scale of digital asset management activity and the expansion of tokenized instrument infrastructure suggest that treasury, custody, and investment operations should reassess exposure to blockchain-based instruments as both an efficiency lever and a diversification tool.
- Capital markets modernization: Tokenization of real-world assets and the emergence of blockchain-native marketplaces indicate that origination, distribution, and secondary trading workflows may be restructured around programmable infrastructure. Early movers in pilot design and partnership formation can influence standards and capture liquidity advantages.
- Payment and settlement optimization: Cross-border payment and peer-to-peer transfer volumes underscore persistent demand for faster settlement and reduced intermediary friction. Organizations with international cash flow requirements should evaluate blockchain-based rails against conventional correspondent banking cost structures and operational risk profiles.
- Regulatory-aligned product design: With clearer frameworks emerging for stablecoins, securities treatment, and crypto-asset services, product roadmaps should incorporate compliance architecture from inception. The cost of retrofitting regulatory alignment is materially higher than designing within an informed regulatory perimeter.
- Competitive positioning: Concentration patterns in the market indicate that a limited set of participants is capturing a disproportionate share of activity. This suggests that late entrants may face increasing barriers to differentiation unless they target underserved segments, specialized use cases, or distinct jurisdictional opportunities.
What the Full Study Delivers
This overview provides the strategic context. The complete PW Consulting Blockchain Finance Market report delivers the operational intelligence required to convert context into decision-ready plans. The study includes detailed segmentation analysis, historical revenue tracking, forward forecasts calibrated across multiple dimensions, protocol-level evaluations, application-domain depth, and regional deployment patterns. It examines competitive positioning with structured company profiles, recent development tracking, and partnership and product-launch timelines that reveal how market leaders are executing. It also integrates the regulatory and infrastructure cost context that shapes deployment economics and risk exposure.
To access the complete dataset, segmentation breakdowns, competitive profiles, and forecast scenarios that support granular strategic planning, we invite you to explore the full report at the source page. The complete intelligence package is designed for executive teams, investment committees, and strategy functions that require precise market structure, credible forward projections, and actionable competitive context to guide 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Blockchain Finance Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: FPGA Market Hits $11.73B in 2025, Projected 10.5% CAGR to $23.6B by 2032
By PW Consulting, 2026-09-16
Navigating the FPGA Inflection Point: Strategic Intelligence for Enterprise Decision-Making in 2026 and Beyond
The global semiconductor landscape is undergoing a profound structural transformation, and within it, the Field-Programmable Gate Array (FPGA) market stands at a critical inflection point. For enterprise technology leaders, procurement strategists, and innovation officers, FPGAs have evolved from niche reconfigurable components into foundational enablers of adaptive compute across artificial intelligence, edge processing, telecommunications infrastructure, and high-reliability defense systems. Yet the sheer velocity of technological advancement, coupled with shifting regulatory frameworks and supply chain realignments, has rendered legacy forecasting models insufficient. This gap between market volatility and the demand for actionable intelligence is precisely why our newly published FPGA Market Research Report has been commissioned and structured. Designed as a strategic decision-support instrument rather than a static data repository, this study maps the trajectory of the FPGA ecosystem from 2026 through 2032, equipping organizations with the contextual depth and analytical rigor required to allocate capital, manage supply exposure, and position product portfolios ahead of competitive cycles.
The Strategic Imperative: Why 2026 Demands a New Analytical Lens
Market history provides the necessary baseline for forward-looking strategy, but 2026 introduces variables that fundamentally alter the planning horizon. The sector’s measured compound annual growth rate of 10.5 percent reflects more than aggregate expansion; it signals a reallocation of investment toward architectures that prioritize flexibility, power efficiency, and cryptographic resilience. Over the past five years, the industry has consistently scaled its value creation, with revenue climbing steadily to an estimated 11.73 billion United States dollars in the 2025 base year and projected to cross the 12.73 billion mark as 2026 takes shape. Looking further downstream, the forecast horizon extends to 23.6 billion dollars by 2032, indicating that the coming years will not merely continue historical momentum but rather accelerate it as system architects embed hardware programmability deeper into AI inference pipelines, advanced communication stacks, and mission-critical platforms.
However, macroeconomic growth curves alone do not dictate enterprise strategy. The strategic value of this research lies in its refusal to treat the market as a monolith. Regional dynamics, product architecture selection, and application-specific adoption curves diverge significantly, and companies that apply uniform assumptions across their operations risk misallocating engineering resources or underestimating procurement constraints. By deliberately synthesizing historical performance data with forward-looking scenario modeling, our report enables decision-makers to anticipate inflection zones where supply constraints, design complexity, or competitive repositioning will create asymmetric advantages. The objective is not to overwhelm stakeholders with fragmented metrics but to distill complex market behaviors into strategic action pathways that can be operationalized within existing product roadmaps, procurement frameworks, and partnership strategies.
Field-Programmable Gate Array (FPGA) Market
Market Architecture and Forward Trajectory: Decoding the Growth Curve
The structural composition of the FPGA market reveals how demand segments are evolving and where enterprise exposure is most concentrated. Product architecture remains a defining variable in both procurement strategy and engineering roadmapping. The market environment continues to be anchored by established platforms that dominate deployment volume, while alternative architecture families serve specialized reliability, security, or power-efficiency niches. Each architecture type carries distinct implications for design lifecycle management, software ecosystem compatibility, and geopolitical supply exposure. Organizations evaluating vendor portfolios must therefore assess not only performance benchmarks but also the long-term viability of toolchains, legacy migration pathways, and the strategic alignment of each architecture with their projected deployment environments.
Application segmentation further underscores the broadening scope of FPGA utilization. Telecommunications, data center infrastructure, consumer electronics, automotive systems, industrial automation, and military or aerospace programs each impose unique performance, certification, and lifecycle requirements. As processing workloads migrate toward disaggregated architectures and domain-specific acceleration, the programmable fabric has become a strategic layer for bridging fixed silicon limitations with evolving algorithmic demands. The interplay between these verticals is increasingly bidirectional: breakthroughs in data center acceleration architectures frequently inform edge deployment optimizations, while stringent environmental and reliability standards in industrial or aerospace sectors drive innovations that eventually cascade into broader commercial applications.
Concentration dynamics add a critical dimension to competitive and procurement strategy. The market remains highly consolidated, with the top three players collectively commanding three-quarters of total industry revenue and the top five reaching approximately eighty-five percent. High concentration implies that partnership negotiations, licensing terms, roadmap alignment, and supply allocation privileges are disproportionately influenced by interactions with a small cohort of dominant suppliers. For enterprises without direct leverage over these ecosystems, the strategic response involves diversified sourcing architectures, co-development arrangements, and early engagement with emerging platform providers that may offer alternative value propositions in targeted application domains. Long-term planning therefore requires a nuanced understanding of which suppliers will dominate next-generation architectural transitions and which will retreat into niche segments as consolidation accelerates.
Competitive Dynamics and Recent Strategic Moves
The competitive landscape is defined by both established scale players and specialized innovators pursuing differentiated architecture strategies. AMD, operating through its Xilinx lineage, continues to anchor high-performance adaptive compute with its Versal architecture and UltraScale+ platforms, targeting AI-adjacent workloads, data center acceleration, and embedded compute scenarios. Intel’s Altera division has reinforced its commitment to the edge and communications segments through Agilex series platforms optimized for high-speed throughput and compact embedded deployments. These two ecosystem behemoths exert structural influence on toolchain standardization, strategic pricing expectations, and downstream design migration pathways, making their product announcements highly consequential for enterprise planning.
Smaller but increasingly influential players are carving out defensible positions by focusing on power efficiency, security hardening, and domain-specific reliability. Lattice Semiconductor has expanded its footprint in low-power and mid-range applications while embedding cryptographic agility into its FPGA families, a move that directly addresses emerging security guidance from government and industrial regulators. Microchip Technology maintains a strong positioning in radiation-hardened and high-assurance environments, supporting defense and space architectures that demand both electromagnetic compatibility and resistance to side-channel vulnerabilities. Efinix continues to advance compact, low-power architectures targeting edge AI and real-time processing workloads, while QuickLogic emphasizes antifuse and radiation-tolerant platforms alongside embedded FPGA intellectual property for specialized defense and industrial deployments. Each of these companies is actively shaping the market through targeted product launches, strategic contracting, and roadmap commitments that redefine what programmable silicon can deliver in constrained or highly regulated environments.
The speed of recent corporate activity illustrates how rapidly the competitive frontier is moving. Early in 2026, Intel unveiled its Agilex 3 family, emphasizing optimized power-performance-size tradeoffs for embedded and edge deployments, with software support cycles and production timelines already established. Later that year, AMD announced next-generation Kintex UltraScale+ devices with substantially expanded memory bandwidth and extended availability horizons, signaling a deliberate push toward long-lifecycle industrial and embedded applications. These announcements were preceded by a series of strategic milestones throughout 2025, including Lattice’s introduction of its post-quantum cryptography-ready FPGA family and QuickLogic’s award of a significant defense contract to advance radiation-hardened technology under trusted microelectronics programs. Together, these developments demonstrate that competition is no longer limited to raw logic density or clock speed; it increasingly centers on cryptographic readiness, supply assurance, software maturity, and alignment with government or industry assurance frameworks.
Structural Shifts Shaping Industry Dynamics
Market growth does not occur in a vacuum. The FPGA sector is simultaneously navigating regulatory evolution, material supply volatility, and assurance-driven procurement mandates that will alter sourcing strategies and design methodologies. In early 2025, government defense authorities released updated security guidance specifically directed at FPGA deployments, emphasizing cryptographic key management, hardware security module compliance, and integrated cryptographic libraries within design flows. Such guidance transforms security from an optional hardening step into a foundational design requirement, with direct implications for vendor evaluation, architecture selection, and lifecycle maintenance. A subsequent revision of best practice documentation further codifies expectations around authentication, auditability, and reproducible build environments, reinforcing the need for supply chain traceability and design process discipline.
Geopolitical and material constraints are introducing parallel pressures. Semiconductor manufacturing dependencies on concentrated raw material sources have become a strategy-informing reality. A substantial share of global silicon production and the overwhelming majority of certain low-purity gallium requirements originate from a single geographic region, and export control actions implemented during late 2024 and early 2025 triggered significant price escalation for gallium-dependent supply chains. While not every architecture depends equally on constrained inputs, enterprises with diversified component sourcing needs or long-duration program commitments must incorporate material availability risk into supplier qualification criteria and inventory planning. This is particularly relevant for platforms pursuing extended availability windows, where procurement continuity across multiple product generations becomes a strategic differentiator.
Defense and space program dynamics are also accelerating specialized FPGA development. The progression into advanced phases of radiation-hardened research contracts signals sustained institutional commitment to securing domestically assured microelectronics for current and future mission architectures. As these programs mature, the resulting technology transfer pathways will influence commercial-grade reliability expectations, testing methodologies, and architectural feature sets, creating downstream benefits that may eventually diffuse into broader industrial deployments. For enterprises operating in or adjacent to regulated environments, tracking the intersection of assurance mandates, material constraints, and architectural innovation is essential to maintaining procurement resilience and avoiding unexpected compliance bottlenecks.
Inside the Report: What Decision-Makers Will Gain
Our research methodology was designed to convert market complexity into executable strategy. Rather than presenting isolated data tables or retrospective summaries, the report is structured around decision-centric analysis that connects market sizing, segmentation behavior, competitive positioning, and environmental dynamics into a coherent strategic framework. Decision-makers will find detailed profiling of core suppliers, including their architectural emphasis, target application domains, recent product milestones, and strategic posture relative to market concentration. This enables procurement teams, corporate strategists, and engineering leadership to evaluate supplier roadmaps against internal deployment timelines, compliance requirements, and long-term availability objectives.
The segmentation analysis is organized to illuminate growth distribution across regions, product architectures, and end-use applications without obscuring the underlying structural drivers. Regional dynamics are examined through the lens of infrastructure investment cycles, adoption maturity, and supply chain proximity, while application-based analysis focuses on workload intensity, certification requirements, and the rate at which programmable acceleration is displacing or complementing alternative silicon solutions. Combined with historical tracking from 2020 through 2025 and a forecast window extending to 2032, these layers allow organizations to calibrate investment timing, prioritize internal capability development, and model multiple adoption scenarios under differing supply or regulatory conditions.
A substantial portion of the report is devoted to operationalizing intelligence. Readers will encounter practical frameworks for evaluating design-tool compatibility, assessing post-quantum readiness, anticipating material-driven cost volatility, and structuring supplier engagement strategies in a highly concentrated market. Regulatory developments, certification expectations, and government-backed research activities are integrated directly into the analysis of market dynamics rather than treated as peripheral commentary, ensuring that compliance and assurance considerations are addressed as strategic variables rather than administrative afterthoughts. By aligning market data with execution-oriented guidance, the study functions as a planning reference that can be applied across capital allocation, sourcing strategy, engineering roadmapping, and partnership development.
Programmable Logic Controller (PLC) Market
Why Act Now: Aligning Intelligence with 2026 Decision Cycles
The window for proactive positioning is narrowing. As product portfolios evolve, toolchain ecosystems mature, and assurance requirements become more explicitly codified, organizations that defer strategic assessment risk finding themselves locked into architectures or supplier relationships misaligned with the next growth phase. The FPGA market’s trajectory suggests that programmable acceleration will remain embedded in the core infrastructure of emerging computing workloads, making early intelligence-gathering and supplier alignment a durable competitive advantage rather than a temporary tactical exercise.
This report is engineered to support that advantage. It provides the contextual map, the competitive intelligence, and the structural analysis necessary to turn market signals into disciplined decision-making. However, the full depth of segmentation behavior, detailed supplier positioning, regional nuance, and scenario-based growth pathways is preserved within the complete research deliverable, where interactive analysis, extended vendor profiling, and decision frameworks are available for teams seeking to operationalize the findings directly within their planning workflows. For executives evaluating 2026 capital deployment, supply strategy, product roadmap alignment, or partnership engagement, the comprehensive report offers the intelligence foundation required to act with precision in a market that rewards foresight.
For detailed analysis of this topic, please visit the official page: Field-Programmable Gate Array (FPGA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com